

DSCR Loans for Rental Property: Qualify on Rent, Not Tax Returns
Finance your next rental property based on the income it generates. Griffin Funding offers DSCR loan programs with flexible terms, including no minimum DSCR, a 620 minimum credit score, and loans from $100,000 up to $4.5 million. Explore your rental financing options below, including a no-ratio program that qualifies you based on your credit, down payment, and reserves, rather than rental cash flow.
Last updated: November 19, 2026
- $4.5MMax loan amount
- 15%-20%Down payment
- No MinDSCR required, No-ratio program available
- 6 daysFastest closing time
 Excellent Customer Service
 Specialized Lending Solutions
 Direct Lender Support
 Dedicated Lending Expertise
 Streamlined Online Mortgage Platform
What is a DSCR Loan?
A DSCR loan, also called a DSCR mortgage, is a loan that qualifies borrowers based on the rental income a property generates, instead of personal income.
If the property’s rental income is greater than the cost of the property’s monthly mortgage payment, including taxes, insurance, and HOA, if applicable (PITIA), the property has a positive debt service coverage ratio (DSCR). This generally means the property has positive cash flow. Here’s how DSCR lenders calculate DSCR:
Gross monthly rent ÷ PITIA (Principal, Interest, Taxes, Insurance, and HOA dues) = DSCR
For example, if a rental property brings in $3,000 in rental income per month, and the total mortgage payment (PITIA) comes out to about $2,650 per month, the DSCR is:
$3,000 ÷ $2,650 = 1.13
To a DSCR lender, a positive DSCR can signal lower lending risk. The property’s rental income has some room to absorb unexpected drops in rental income or increases in monthly housing expenses.
DSCR lenders prefer to see a DSCR of at least 1.0, meaning that the property’s rental income exactly covers the full mortgage payment.
Griffin Funding has no minimum DSCR requirement for DSCR loans, and requires no tax returns, W-2s, or DTI calculation. Investors can also choose a no-ratio DSCR loan, where the property’s DSCR isn’t used for qualification at all. See DSCR Loan Programs below for the different DSCR programs Griffin Funding offers.
We Fund DSCR Loans Every Day
Griffin Funding is one of the top direct-to-consumer DSCR lenders in the nation. Don’t just take our word for it. Here are the numbers.
From January 1 through October 31, 2026, Griffin Funding closed 754 DSCR loans totaling $228M. Of those loans, 78 (totaling $27.2M) funded in the last month alone. Our October data shows that 67% were DSCR cash-out refinances by investors pulling equity from their properties, 27% were DSCR rental purchases, and 6% were rate-and-term refinances. The average loan size was $351,546, with individual loan amounts reaching $3M.
Griffin Funding brings hands-on DSCR lending experience to rental property investments of varying sizes, and it’s simply what we do best. DSCR loans account for 42% of our total funded volume this year, and the pace is accelerating: our year-to-date volume accounts for over a quarter of everything we’ve ever closed. All told, Griffin Funding has closed more than 2,366 DSCR loans for over $726 million.
Whether you’re a first-time investor or an experienced landlord expanding your portfolio, you’re working with a team that understands the nuances of investor financing. We pair a streamlined online application process with our proprietary AI underwriting platform, which was featured in HousingWire (September 2025), to achieve fast, successful closings. Griffin Funding has funded files in as little as 6 days, with an average of 34 days.
Griffin Funding is regulated by the CFPB and approved by HUD. It is licensed in 47 states plus D.C. and funds DSCR loans in all 50 states. We document every term, rate, fee, and any prepayment penalties in writing upfront, and give advance notice if anything changes.

Everything real estate investors need to know about DSCR loans, in 20 minutes.
Griffin Funding DSCR Loan Requirements

Eligible properties
DSCR loans are for rental properties only, including 1-4 units, condos, townhomes, and short-term rentals.

DSCR and no-ratio options
No minimum. Griffin Funding also offers a no-ratio program where DSCR isn’t used to qualify at all.

Down payment or equity
The standard down payment is 20%. 15% for borrowers with 740+ FICO, for loans up to $1M (program conditions apply).

Credit score
620 minimum credit score. Griffin borrowers are averaging a credit score of 732 in 2026.

Loan amount
$100,000 to $4.5M, subject to underwriting.

Appraisal and qualifying rent
Required. Used for value and rental income verification.

Ownership
Borrow in your own name or through a U.S. LLC with a personal guarantee. Other business entities and certain trusts may qualify, depending on the program.

Cash reserves
Typically 3-6 months of PITIA, available after closing. 3 months for loans up to $1M; 6 months for loans above.
For more details on credit, down payment, property, and cash reserve requirements for DSCR loans, see the complete DSCR loan requirements guide.
Today’s DSCR Loan Rates
In November 2026, DSCR loan rates start at 6.5% for 1-year adjustable-rate mortgages (ARMs) and 6.875% for 30-year fixed, 40-year fixed, and 5-year ARM loans.
Conventional loan rates aren’t necessarily cheaper than DSCR loan rates. Conventional investment property loans tend to carry additional pricing adjustments (LLPAs) that can narrow the gap between conventional and DSCR loan rates today.
See below for DSCR mortgage rates today.
“When I advise real estate investors on DSCR loans, the first step is comparing the payment difference between an interest rate with no points versus a lower rate with points. Recently, I worked with a borrower who could save $190 per month by buying down the rate. But since their plan was to refinance in four to five years and use equity to purchase another property, they chose the higher rate with no points. That strategy kept more cash in their pocket today, while rental income still covered the mortgage. By waiting to refinance when rates are lower, they’ll preserve liquidity now and use future equity to keep building their portfolio.”
Adam Ruvelson, Orange County Branch Manager at Griffin Funding, NMLS# 1283827
DSCR Loan Programs
Purchase
A DSCR purchase loan qualifies you based on the property’s expected rental income instead of your personal income. No W-2s or tax returns needed. DSCR loan requirements include a standard 20% down, or 15% for borrowers with a 740+ credit score on loan amounts up to $1M, an eligible rental property, and a 620 minimum credit score. Griffin Funding DSCR purchase loans range from $100,000 to $4.5M, subject to underwriting.
Rate & Term Refinance
A DSCR rate-and-term refinance moves you out of high-rate hard money or bridge debt into a stable 30-year or 40-year term, or lowers the rate on an existing loan, with interest-only options to maximize cash flow.
No-Ratio DSCR
A no-ratio DSCR loan looks at your credit and down payment for qualification, instead of the property’s rental income. Up to 75% LTV for borrowers with a 700+ credit score, for loans up to $1M. This option suits high-value, low-yield markets where rent may fall short of PITIA.
SOFR ARM
A SOFR ARM DSCR loan offers our lowest starting rates for 6-month and 1-year adjustable terms. Fully amortized or interest-only options. Best for short- to medium-hold strategies.
Cash-Out Refinance
A DSCR cash-out refinance lets you pull equity from an existing rental, allowing up to 80% LTV for properties with 1.0 DSCR or higher. No seasoning period required, so you can refinance sooner after purchasing. Best fit for BRRRR strategies.
DSCR HELOAN & HELOC
A DSCR HELOAN or HELOC lets you tap into your rental’s existing equity to fund renovations and repairs, purchase another investment property, or consolidate debt. It sits behind your first mortgage so you can keep your existing rate. Choose a fixed-rate lump sum or a revolving line of credit depending on how you need your funds.
Rental Income Plus Assets
A rental income plus assets DSCR loan raises your total qualifying income by combining the property’s rent with liquid assets. Best for investors whose rental income alone falls short, without needing to pledge those assets as collateral.
Pros and Cons of Griffin Funding DSCR Loans
Pros
- No tax returns or W-2s for income verification
- No employment verification
- More streamlined application compared to conventional loans
- Loan amounts from $100,000 to $4.5M
- Cash-out refinances up to 80% LTV
- Interest-only options available
- Short-term rentals eligible
- Borrow through an LLC
Cons
- Larger down payment required than owner-occupied loans
- Rates can run higher, though LLPAs have narrowed the gap
- Loan size tied to the property’s cash flow
- Rental properties only
- Most carry prepayment penalties
- No fixer-uppers
- Unique and rural properties can be harder to finance
If you don’t fit conventional lending guidelines neatly, DSCR loans offer a flexible alternative for borrowers investing in rental properties.
DSCR loans skip personal income and employment verification, letting the property’s rental income carry the file. However, the property must be rent-ready or generating income to qualify. Most DSCR loans also carry a prepayment penalty for paying the loan off early, but Griffin Funding offers options without one, typically in exchange for a higher interest rate.
With investor and DSCR loans now making up roughly a third of non-QM volume, according to July 2026 rate-lock data, you have plenty of DSCR lender options to compare. Shop around for the best rates and terms for your property and profile, and get these details in writing.
Because DSCR loans are business-purpose loans, they are not “qualified” mortgages under federal TRID disclosure laws, which require lenders to provide borrowers with standardized disclosures and delivery timelines. These documents help borrowers better fully understand loan terms and closing costs before closing. Some lenders may take advantage of limited disclosure requirements to keep terms vague until closing.
Griffin Funding will always put any rates, points, fees, and prepayment penalties in writing upfront on either a loan estimate or term sheet, depending on the file. Borrowers can take this information with them as they compare DSCR loan programs and DSCR lenders for their rental investments. We also disclose any changes before they happen, so borrowers aren’t caught by surprise at the closing table.
Whether you’re in the planning phase and doing research, or you’re ready to get quotes, Griffin Funding offers free tools and resources to guide your investment decisions.
Run your numbers with our free home value estimator and free rent estimator to see how your property fares with a DSCR loan. Or reach out to a Griffin Funding loan officer licensed in your state for more DSCR program information.
What to Watch For
“You need to make sure you figure out what kind of prepayment penalty is being put on the loan because, in many cases, that’s not disclosed. DSCR loans don’t follow federal disclosure guidelines, so a lender technically doesn’t need to disclose anything at all until the end. We do the opposite: your rate, fees, and prepayment penalty are in writing upfront, and we vet the numbers against the rental income, so the loan has a much higher chance of closing where it starts rather than changing along the way.”
Guy Troxler, Senior Loan Officer with 7 years of experience in the mortgage industry, NMLS# 1642169
For a full breakdown of DSCR loan advantages and tradeoffs, see our complete guide to DSCR loan pros and cons.
Estimate your ratio before you apply: choose purchase, short-term rental, or cash-out refinance, enter the rent and the payment, and the calculator does the rest.
Want the full math? See how DSCR is calculated,
with worked examples and what to do if your ratio comes up short.
DSCR Calculator
DSCR Loans in All 50 States
Griffin Funding offers DSCR loans in all 50 states, plus Washington, D.C., and we hold a license in every state that requires one for DSCR lending.
To help investors better understand how local rents, property taxes, insurance costs, and landlord regulations can change the math in their target market, we’ve created DSCR loan guides for every state, with worked DSCR examples based on typical home values in various metros. Find your state on our DSCR Loans by State page to learn more.
“Great team to work with from application through closing and afterwards for follow up needs. Very fast turnaround on rental property cash out mortgage. Have used them twice for this product and will again if I need to. Highly recommend for rental real estate investors!”
Sara J.
FAQ
Frequently Asked Questions
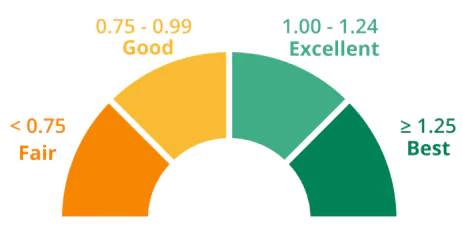
A good DSCR is a ratio of at least 1.0, which means that the property generally brings in enough income to cover the property’s housing expenses. This leaves little room for mishaps, though, and a vacant unit or higher monthly expenses can put you in the red. Most lenders prefer a 1.25 ratio or higher, which unlocks the best pricing, and may decline files below that. Griffin Funding has no minimum DSCR, so borrowers with a sub-1.0 DSCR may still qualify for a DSCR loan.
Griffin Funding DSCR loans require a minimum credit score of 620. Higher credit scores can unlock better rates and, potentially, a lower down payment requirement. Griffin Funding offers a 15% down payment option at a score of 740 and above, for loans up to $1M. In 2026, Griffin Funding DSCR borrowers are averaging a 732 credit score.
You’ll need a 20% down payment, which is the standard down payment requirement for DSCR loans. For borrowers with stronger credit (740+), Griffin Funding may offer an option for 15% down on loans up to $1M, subject to specific program terms. Making a larger down payment can improve your DSCR by lowering the monthly payment the rent needs to cover, and may also improve your rate. DSCR cash-out refinances do not require a down payment. Explore our DSCR loan down payment requirements guide to see where down payment funds can come from. Griffin Funding’s average DSCR loan down-payment for 2026 currently sits at 25%.
Not much anymore. Conventional loans on investment properties typically carry agency loan-level price adjustments that add 0.5% to 0.75% to the owner-occupied rates you see advertised. This narrows the gap between conventional investor pricing and current DSCR loan rates. However, your exact DSCR rate depends on your credit score, DSCR, down payment, points, and your prepayment penalty term. See how LLPAs affect your rate.
Yes. Griffin Funding has no minimum DSCR for DSCR loans, allowing files to qualify with ratios that fall below 1.0, while most lenders will decline these files. Keep in mind that a DSCR below 1.0 means that the property’s rental income doesn’t fully cover its housing expenses, so you will still need to be able to cover those costs separately. Griffin Funding also offers a no-ratio program that doesn’t use the property’s cash flow to qualify, and looks at a borrower’s credit and down payment instead.
Yes. You can close a DSCR loan through a U.S. LLC, or hold the property in a different entity or trust, including a partnership, corporation, S corp, or revocable trust, depending on the DSCR program. This can help shield your personal assets from business-related claims, and keep your personal and rental finances separate. However, lenders may still require a personal guarantee if you close a DSCR loan in an LLC, which makes you responsible if the loan defaults. See our full guide to buying rental property through an LLC for more details.
“DSCR loans are great financing alternatives to have borrowers build wealth along with their portfolio without showing any personal income to qualify. We don’t even verify if you have a job or not; we look solely at the property to see if the rent covers the payment. Another reason to take advantage of the DSCR loan is you can close in an LLC, which keeps the mortgage off your personal credit report.”
– Cody Unger, Scottsdale Branch Manager at Griffin Funding, NMLS# 1295308
Most DSCR loans carry prepayment penalties, typically one to five years. The term you choose affects your rate: a longer prepayment penalty period usually carries lower rates, and buying out a penalty typically carries a higher rate. See how prepayment penalties work. Griffin Funding discloses all prepayment penalty terms in writing upfront.
Griffin Funding’s fastest DSCR closing is 6 days, with an average of 34 days. Because DSCR loans skip income and employment verification, the qualification process tends to be more streamlined compared to a conventional loan. Actual pacing depends on the appraisal, title work, and borrower responsiveness, which includes having all your documents ready when the time comes. Prepare necessary documents ahead of time to streamline closing.
Generally, no. DSCR loans closed through an entity, such as an LLC, aren’t reported to consumer credit bureaus, so they don’t typically show up on your personal credit. However, closing through an LLC with a personal guarantee makes you responsible for the loan if the LLC fails to repay, which may reach your personal credit. Other lenders may also consider the debt when you apply for a future loan.
Yes. We allow short-term rentals (STRs) like Airbnb to qualify for DSCR loans. To document short-term rental income, we use market rent from the appraisal, documented rental history, or AirDNA-style market data, depending on the program. Note that short-term rental files may have different loan requirements than long-term rental properties, including coverage minimums and LTV limits. If you plan to use a DSCR loan for a short-term rental or Airbnb, make sure your market permits STR use. Bring your revenue history to one of our loan officers so we can match you to the right program. We permit short-term, mid-term, and long-term rental strategies for DSCR loans. See more in our guide on DSCR loans for Airbnb properties.